In a vendor contract, indemnification means a promise by one party to pay for the financial losses, legal costs, and damages suffered by the other party if specific third-party claims or disputes occur.
When hiring an outside supplier, consultant, or software provider, both parties sign an agreement that allocates financial risk if something goes wrong. At BoringMagazine.Co, our goal is to explain complex business terms in plain language. Indemnification provisions are frequently negotiated because they shift substantial legal liabilities from one firm to another.
How Indemnification Works in Business Contracts
Indemnification functions as a private contractual shield between two commercial entities. The party promising protection is the indemnitor, while the party receiving protection is the indemnitee. If an outsider sues the client because of the vendor’s work, the vendor covers the defense costs, legal settlements, and court awards.
Commercial agreements trigger indemnification only under defined circumstances. Common triggers include material breach of contract, gross negligence, intentional misconduct, or regulatory violations. If a customer faces a copyright lawsuit because a contractor supplied unlicensed material, the contractor must pay the resulting financial claims.
As explained across our Business guides, clear risk allocation prevents operational disruption. Without an indemnity clause, an injured buyer must file a separate lawsuit against the vendor to recover losses. An indemnity clause establishes a direct path to reimbursement, saving time and litigation costs.
The Three Core Obligations: Defend, Indemnify, and Hold Harmless
Commercial contracts often combine three distinct legal duties into a single clause: defend, indemnify, and hold harmless. Each term imposes a distinct legal responsibility.
- Duty to defend: The vendor must hire lawyers and pay ongoing legal fees immediately after a third-party claim is filed, regardless of whether liability is proven.
- Duty to indemnify: The vendor must pay the actual damages, judgments, or settlements after liability is established.
- Duty to hold harmless: The vendor agrees not to hold the client liable for the covered loss, releasing the client from related claims.
Separating the duty to defend from indemnification is significant for small firms. Defending a commercial lawsuit can cost thousands in attorney fees before a case concludes. An immediate duty to defend forces a small vendor to pay retainer fees as soon as a claim is filed.
Unilateral vs. Mutual Indemnification: Key Differences
Indemnity provisions follow two basic structures: unilateral or mutual.
In a unilateral clause, only one party provides legal protection. Large buyers often use standard templates demanding unilateral protection from small suppliers. The vendor shields the buyer from third-party lawsuits, but the buyer gives zero reciprocal protection to the vendor.
In a mutual clause, each party protects the other against risks under their direct control. The vendor indemnifies the client against software defects or copyright claims, while the client indemnifies the vendor against claims stemming from customer-provided data.
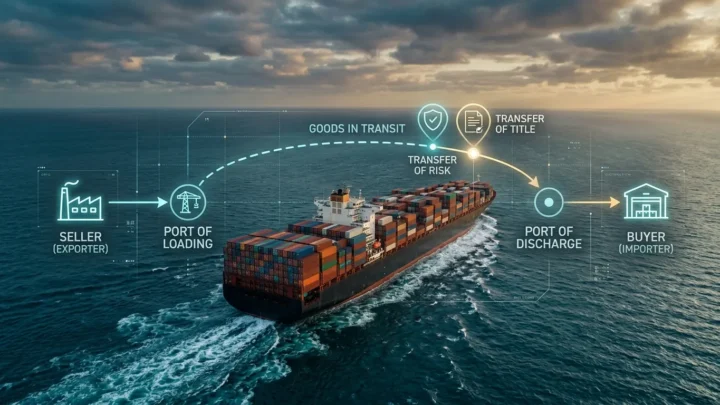
Contractual risk-shifting mechanisms appear across commerce. Business operators evaluate similar trade-offs when reviewing commercial licensing agreement terms, where intellectual property ownership dictates third-party liability. Similarly, shipping agreements rely on FOB destination shipping terms to define when physical transit risk shifts to the buyer. Indemnification clauses perform an identical function for service relationships.
Real-World Examples of Vendor Indemnity Scenarios
To see how indemnity functions in practice, consider three common business situations:
- Intellectual property disputes: A software contractor builds an online store for an e-commerce retailer. If the contractor incorporates proprietary code owned by a third party, that owner might sue the retailer. Under an intellectual property indemnity clause, the contractor must fund the store’s legal defense and pay any settlement.
- On-site property damage: A cleaning contractor works inside a corporate facility. A technician leaves a valve open, causing water damage that ruins an adjacent tenant’s equipment. The tenant sues the property owner. The indemnity clause requires the cleaning contractor to resolve the claim.
- Data security incidents: A payroll processor suffers a data leak exposing confidential employee records. Affected workers sue their employer. If the agreement includes a data breach indemnity clause, the payroll vendor must cover the employer’s legal costs and settlement expenses.
Common Mistakes Small Service Providers Make
Small businesses often accept standard contracts without negotiation. These common oversights create severe financial exposure:
- Assuming general liability insurance covers all indemnity promises: General liability policies cover bodily injury and property damage, but exclude breach of contract, copyright claims, and performance guarantees. Uncovered promises must be paid from company cash reserves.
- Accepting uncapped indemnity obligations: Many master agreements lack financial limits on indemnity. Without a cap, a single dispute can threaten company solvency.
- Agreeing to defend mere allegations: Some contracts require defense for any claim alleging a fault. Even if an accusation is baseless, the vendor might have to fund an expensive defense.
- Accepting broad phrasing: Clauses containing phrases like any claims arising out of or related to this agreement make vendors liable for events beyond their operational control.
How to Negotiate and Limit Indemnification Risk
Service providers can reduce exposure by proposing several standard modifications during contract negotiations:
First, make the clause mutual. If a client expects protection against vendor errors, the client should provide reciprocal protection against customer mistakes.
Second, cap financial liability. Restrict indemnity obligations to available insurance coverage or to total fees received under the contract over the prior twelve months.
Third, add clear carve-outs. Exclude indemnity obligations if losses stem from the client’s direct negligence, unauthorized modifications, or failure to follow instructions.
Fourth, require formal notice. Mandate that the client provide prompt written notice of any third-party claim, grant you control over the legal defense, and prohibit settlements without your consent.
This guide provides general business information, not legal or financial advice. Contract rules differ by jurisdiction. Small business owners should consult a qualified commercial contract attorney before signing binding agreements.
FAQ
Does business insurance cover indemnification obligations?
Business insurance does not automatically cover every indemnification obligation in a vendor contract. Commercial policies cover bodily injury and physical property damage, but they regularly exclude contractual breach liabilities, copyright infringement, or software errors. Small businesses should review exclusions with a qualified insurance broker to confirm coverage matches contractual commitments.
What is the difference between indemnification and a limitation of liability?
An indemnification clause specifies who pays for specific third-party claims, while a limitation of liability sets an overall dollar ceiling on total contract damages. Buyers often seek to exclude indemnity from liability caps, which exposes vendors to unbounded risk. Service providers should negotiate to ensure indemnity obligations remain subject to the general liability cap.
Can a small vendor negotiate an indemnification clause?
Yes, small vendors can routinely negotiate indemnification clauses by requesting mutual obligations, adding monetary caps, and narrowing trigger language. Corporate procurement teams often start with aggressive boilerplates, but they regularly accept reasonable revisions that confine indemnity to intentional misconduct or material breaches.