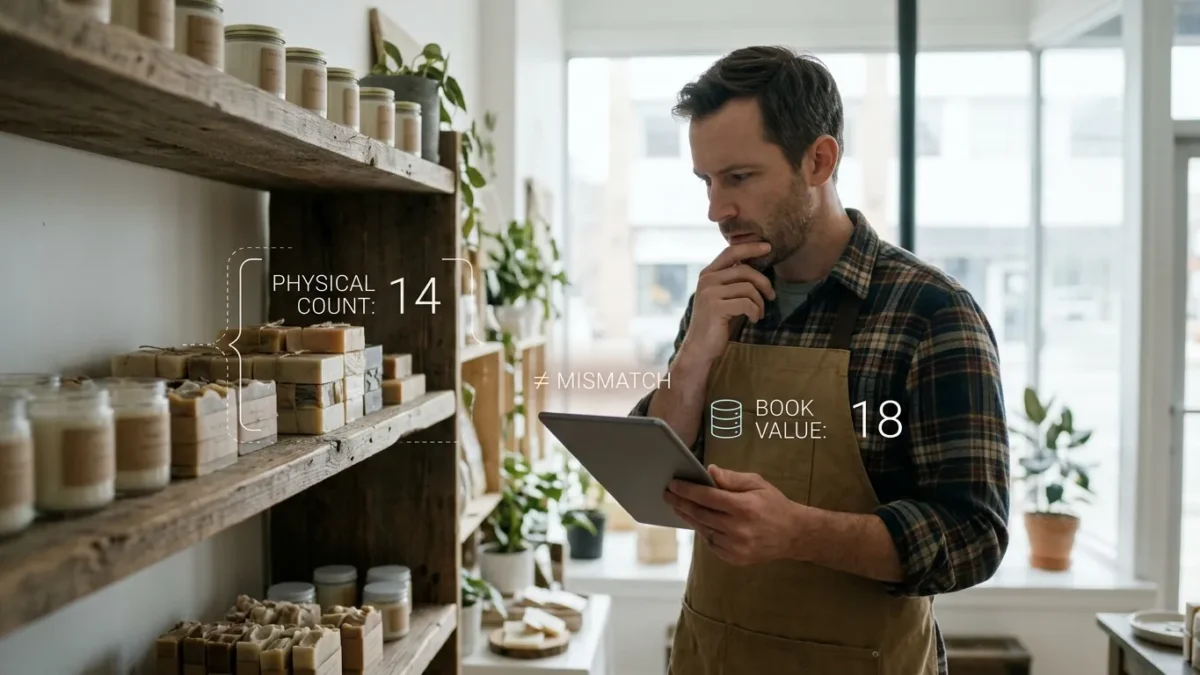
To record an inventory write-off in bookkeeping, debit either an inventory write-off expense account or Cost of Goods Sold and credit the inventory asset account by the historical cost of the unusable items.
Every business that sells physical goods eventually encounters broken products, expired goods, or missing items. In accounting terminology, unexplained loss is known as inventory shrinkage, while the formal removal of unsellable stock from your financial ledger is an inventory write-off. Handling these events properly ensures your balance sheet reflects actual assets and keeps your income statement accurate for tax purposes.
Small business owners often worry that recording discarded merchandise requires expensive enterprise software or complex calculations. In reality, standard double-entry bookkeeping handles write-offs cleanly with basic journal entries. At BoringMagazine.Co, we focus on clear, functional operational systems that keep your company financially sound without unnecessary administrative friction.
How an Inventory Write-Off Works in Small Business Bookkeeping
Inventory represents an asset purchased with the expectation of generating revenue. As long as items sit in your warehouse or store shelves ready for sale, their purchase cost remains on your balance sheet under current assets. You only recognize that expense on the income statement as Cost of Goods Sold (COGS) once the item is actually sold.
When products are stolen, broken beyond repair, spoiled, or rendered obsolete, they lose their economic utility. Because these goods can no longer generate revenue, leaving them on the balance sheet overstates company assets and gives owners a false impression of working capital. Writing off inventory removes the dead stock from the balance sheet and recognizes the financial loss as an expense in the current accounting period.
Shrinkage covers the broad gap between recorded inventory numbers and your physical count. If your software shows 100 units on hand but a physical audit only reveals 94 units, those six missing units represent shrinkage. A write-off is the formal ledger action you take to reconcile that difference or discard known defective items.
Direct Write-Off Method vs. Allowance Method
Small businesses generally choose between two accounting approaches when handling unsellable stock: the direct write-off method and the allowance method.
The direct write-off method is the most common technique for small, privately owned operations. Under this method, you record the expense at the exact moment you identify the item as unsellable. If a pallet of ceramic mugs shatters in the storeroom on Tuesday, you enter a journal entry that same week to write off the lost value. This method requires minimal setup and matches the cash flow reality of small firms.
The allowance method creates a reserve account, known as an Allowance for Obsolete Inventory, which acts as a contra-asset account against your total inventory. Under this framework, management estimates expected future shrinkage at the end of each reporting period and pre-funds that reserve through an expense entry. When specific items are discarded later, the loss is charged against the reserve rather than directly hitting the income statement.
Public companies and firms following strict Generally Accepted Accounting Principles (GAAP) must use the allowance method to match expenses with the revenue periods they helped generate. For most independent shops, service contractors, and small retailers using tax-basis accounting, the direct write-off method is fully compliant and far easier to maintain. Readers dealing with complicated multi-entity valuations should consult a licensed Certified Public Accountant (CPA) to confirm which method aligns with their reporting framework.
Step-by-Step Process for Recording a Write-Off
Recording an inventory write-off requires a systematic workflow to prevent ledger imbalances and internal confusion. Following a disciplined procedure keeps your books clean and audit-ready.
- Segregate the affected goods: Physically remove the damaged or expired products from active storage to prevent employees from selling them accidentally.
- Determine the correct cost basis: Calculate the exact original cost paid for the items, including freight-in costs if capitalized. Never calculate write-offs using retail sale prices.
- Adjust inventory management software: Update your point-of-sale or inventory tracking program to deduct the exact units and stock-keeping units (SKUs) from active counts.
- Create the financial journal entry: Post the adjustment in your general ledger to reconcile the balance sheet with physical reality.
- File supporting records: Attach physical disposal receipts, photos, and manager approvals to the journal voucher.
When posting the entry, the specific accounts you select depend on the size of the loss. If the loss is small and part of normal operations, many bookkeepers debit Cost of Goods Sold directly:
- Debit: Cost of Goods Sold
- Credit: Inventory Asset
If the loss is substantial, unusual, or caused by a singular event such as a pipe leak, debiting COGS directly will distort gross profit margins. In that scenario, use a dedicated operating expense line:
- Debit: Inventory Write-Off Expense (Loss on Inventory Disposal)
- Credit: Inventory Asset
For more detailed breakdowns on expense structuring and general ledger best practices, explore our Business guides.
Handling In-Transit Losses and Damaged Shipments
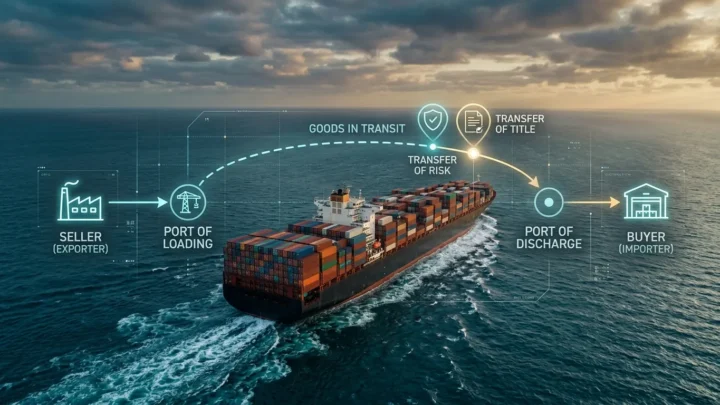
Before recording a write-off on goods that arrived damaged from a supplier, determine who legally owned the items when the damage occurred. Writing off inventory you did not yet own can create tax errors and cause you to miss reimbursement opportunities.
Ownership transitions are governed by shipping terms on purchase orders and bills of lading. If goods were bought under FOB shipping point terms, ownership transferred to you as soon as the carrier loaded the shipment. In that situation, your company bears transit risks, meaning you must record the inventory, log the damaged portion, and file an insurance claim with the freight carrier.
Conversely, under FOB destination terms, the vendor maintains ownership until the boxes reach your receiving dock. Damaged goods arriving under FOB destination terms should be rejected upon delivery or set aside for vendor credit. You should not record a write-off for items that never became company property.
If disputes arise over responsibility for transit issues or defective goods, review indemnification clauses in vendor agreements to determine whether your supplier is obligated to absorb financial losses caused by their contracted third-party carriers.
Documentation Requirements and Recordkeeping Standards
Tax authorities do not allow businesses to deduct inventory write-offs without verifiable documentation. The Internal Revenue Service expects clear proof that written-off stock was genuinely destroyed, abandoned, or discarded, as detailed on the IRS website.
To protect your deductions during an audit, maintain an internal disposal log containing the following information for every write-off event:
- The date the damage or loss was identified and processed.
- The item SKU, item description, and total unit quantity discarded.
- The historical cost per unit and total dollar write-off amount.
- The precise reason for disposal, such as water damage, expiration, or theft.
- The final method of destruction, such as hauling to a local landfill, shredding, or donation.
- Signatures of both the employee performing disposal and the supervising manager.
Retain these logs alongside digital photographs of the damaged items and any third-party disposal receipts. Store these records for at least three to seven years to satisfy statutory tax examination windows.
Common Mistakes to Avoid When Writing Down Inventory
Simple bookkeeping misunderstandings can lead to distorted financial statements and tax compliance penalties. Small business operators should watch out for several recurring traps.
The most frequent error is recording the write-off at the retail sale price instead of the item cost. Writing off retail value claims an artificial deduction for profit margins that were never earned. Write-offs must strictly reflect the lower of cost or net realizable value.
Another common mistake is updating the general ledger without updating your inventory tracking software. If your accounting ledger drops by $2,000 but your warehouse management tool still shows the units on the shelf, your staff will continue trying to fulfill orders with ghost inventory.
Businesses also make the mistake of waiting until the end of the year to record all write-offs during an annual physical count. Delaying entries masks inventory problems, hides theft trends from management, and bunches expenses into the fourth quarter rather than presenting an accurate view of year-round financial performance.
FAQ
Can a small business write off damaged inventory at its retail selling price?
No, you must record inventory write-offs at historical purchase cost rather than retail selling price. Bookkeeping standards permit businesses to deduct only the actual capital spent to acquire the goods. Deducting projected sales prices improperly inflates business expenses and violates tax rules.
What is the difference between an inventory write-off and an inventory write-down?
An inventory write-off removes the full cost of goods that have zero remaining economic value, while a write-down reduces the book value of items that can still be sold at a discount. If an item cost $50 and can now only sell for $20, you write down the value by $30. If it cannot be sold at all, you write off the full $50.
Does an inventory write-off reduce net taxable income?
Yes, recording an inventory write-off creates a legitimate business deduction that reduces net taxable income for the tax year in which the write-off occurred. The deduction occurs either by increasing Cost of Goods Sold or through a dedicated operating expense line. Businesses must preserve disposal records to validate the deduction under audit.