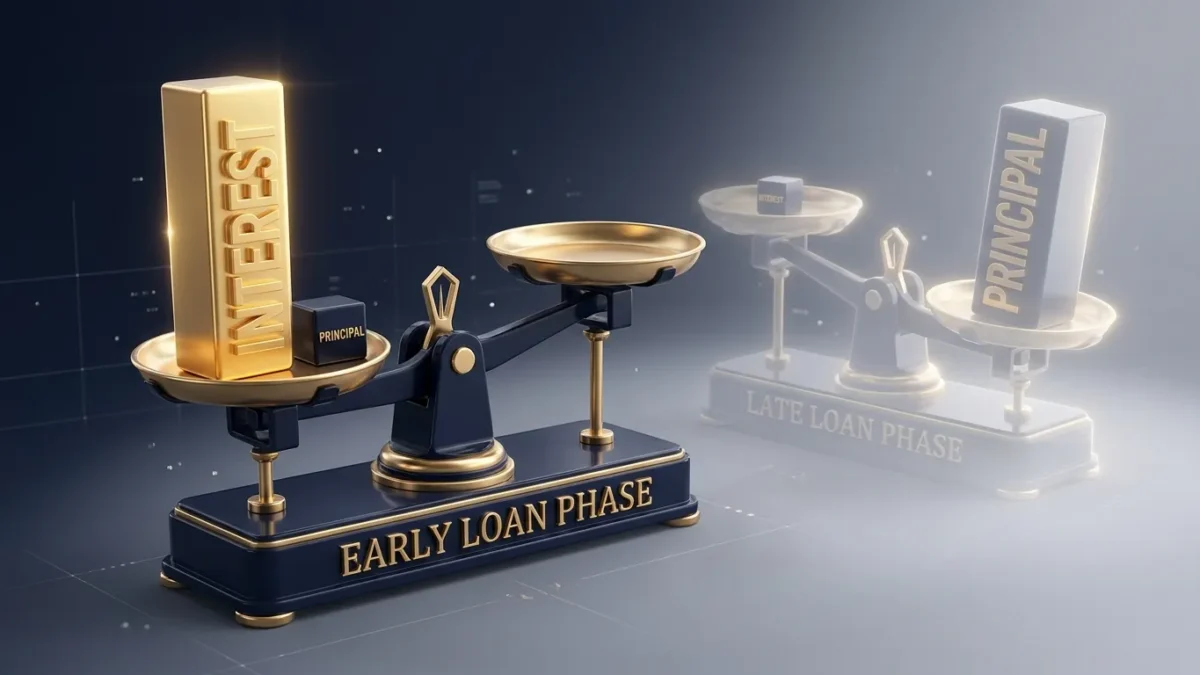
Mortgage interest appears front loaded because interest charges are calculated directly from your remaining loan balance, which is at its largest when you first take out the loan. In a standard fixed-rate mortgage, you pay the exact same total amount every month. Because your debt is largest at the beginning, the monthly interest cost takes up the lion’s share of that fixed check, leaving only a modest portion to chip away at the principal.
Many new homeowners open their first annual statement and feel shocked. They might have sent thousands of dollars to their loan servicer over twelve months, only to see the loan balance barely drop. At BoringMagazine.Co, we believe that understanding the exact mechanics of everyday financial products removes unnecessary confusion and helps borrowers make smarter choices with their money.
How Amortization Schedules Work
Amortization is the process of spreading out a loan into a series of equal periodic installments. To keep your monthly payment predictable over fifteen or thirty years, lenders use a mathematical formula that balances interest and principal across the life of the loan.
A typical residential mortgage is a fully amortizing loan. This design guarantees that if you make every scheduled monthly payment on time, your loan balance will hit zero on the final due date. If lenders required you to pay equal principal installments every month alongside accrued interest, your initial monthly payments would be massive, shrinking over time. Most household budgets cannot manage erratic or top-heavy bills. Instead, the standard structure keeps the total monthly bill constant while the underlying components shift.
In the early years, the monthly payment consists primarily of interest charges. In the final years, that ratio flips completely, and the vast majority of each installment goes directly toward principal. You can explore our collection of our Finance guides to see how different borrowing structures influence long-term borrowing costs.
The Math Behind Monthly Interest Calculations
The calculation that determines your monthly interest is simple arithmetic. The lender does not use complex algorithms or arbitrary penalties to front load the interest. Instead, they apply a simple interest formula based on the outstanding principal balance at the start of each billing cycle.
Here is the three-step sequence that occurs every month:
- Calculate monthly interest: The servicer divides your annual interest rate by twelve to determine the monthly interest rate. Then, they multiply that rate by the outstanding balance you still owe.
- Apply the payment to interest first: When your payment arrives, the servicer covers the newly calculated interest charge for the preceding month.
- Apply the remainder to principal: Whatever money is left over from your fixed payment goes toward reducing your outstanding principal balance.
Because the principal reduction is small in early months, the balance going into the next month is only slightly lower. Consequently, the interest charge for month two is only a few cents or dollars lower than month one. This dynamic causes the slow, gradual pace of equity accumulation at the start of the loan term.
A Concrete Example: Breaking Down a $300,000 Mortgage
To see how this works in practice, examine a standard thirty-year fixed-rate mortgage of $300,000 at a 6% annual interest rate. The monthly principal and interest payment for this loan is $1,798.65.
In the first month, your outstanding principal balance is the full $300,000. Your monthly interest rate is 6% divided by twelve months, which equals 0.5% (or 0.005). When you multiply $300,000 by 0.005, the interest owed for the first month is exactly $1,500.00.
When you submit your $1,798.65 payment:
- Interest charge: $1,500.00
- Principal reduction: $298.65 ($1,798.65 minus $1,500.00)
- New remaining principal balance: $299,701.35
In month two, the interest calculation runs on the updated balance of $299,701.35. Multiplying this new balance by 0.005 results in an interest charge of $1,498.51. Because the interest charge dropped by $1.49, your principal contribution grows by $1.49 to $300.14. The new balance drops to $299,401.21.
This tiny shift repeats twelve times a year. By year fifteen (payment 180), your remaining principal balance drops to roughly $208,000. At that point, your monthly interest fee is around $1,040, and your monthly principal reduction climbs to roughly $758. By year twenty-five (payment 300), the balance is around $89,000. The monthly interest cost drops to about $445, leaving over $1,350 of your monthly payment to wipe out principal.
Common Misconceptions About Front Loaded Interest
Many borrowers believe that lenders use deceptive accounting methods to extract their profits early. A common rumor claims that if you sell or refinance your home after five years, the bank keeps unearned interest. That is incorrect. Under modern simple-interest mortgage rules, you only pay interest on the money you actually borrowed for the specific days you held the debt.
Another frequent misunderstanding occurs when homeowners see their monthly housing payment increase and assume the lender altered the amortization schedule. On a fixed-rate loan, your principal and interest payment never changes. Variations in your total monthly housing bill almost always stem from escrow adjustments for property taxes or homeowner insurance premiums. You can read our detailed breakdown on why monthly escrow payments fluctuate to understand how escrow deficits work.
Similarly, borrowers setting up automated drafts often worry about processing delays creating late fees or distorted interest charges. Reviewing how automatic ACH loan payments clear helps clarify how banking networks post funds. For official guidance on federal consumer lending rules, borrowers can consult resources published by the Consumer Financial Protection Bureau.
Strategies to Pay Down Principal Faster
Because interest depends strictly on your outstanding balance, reducing that balance sooner shrinks every future interest charge. You do not need to accept thirty full years of heavy interest if your household cash flow allows for extra payments.
Homeowners often use these simple methods to accelerate debt payoff:
- Designated principal payments: Send an extra fifty, one hundred, or two hundred dollars each month specifically designated toward principal. This directly reduces the starting balance for next month’s interest formula.
- Biweekly payment schedules: Pay half of your standard monthly payment every two weeks. Since there are fifty-two weeks in a year, you make twenty-six half-payments, which equals thirteen full payments per year instead of twelve.
- Lump-sum contributions: Apply tax refunds, work bonuses, or inheritance funds directly to the loan principal to cut years off the loan term.
Before applying extra funds toward your loan balance, verify with your loan servicer that there are no prepayment penalties and confirm that payments apply to principal rather than future interest. Readers should speak with a qualified financial advisor to determine whether accelerating mortgage payoff makes sense compared to investing or paying off higher-interest consumer debts.
FAQ
Is front loaded mortgage interest an extra fee or bank penalty?
No, front loaded mortgage interest is neither an extra fee nor a lender penalty. It is the natural mathematical result of calculating simple monthly interest against a large outstanding loan balance. As you pay down the debt balance, the interest charges decrease accordingly.
Can you avoid paying high interest in the early years of a mortgage?
You cannot change the basic mathematical formula of an amortization schedule, but you can minimize total interest by choosing a shorter loan term or paying extra principal. Selecting a fifteen-year mortgage or sending additional principal payments forces the balance down much faster, reducing early interest costs.
Does refinancing reset your amortization schedule?
Yes, refinancing into a new thirty-year loan resets your amortization schedule back to year one. While refinancing to a lower interest rate can lower your monthly obligation, starting a brand-new thirty-year term means your payments will once again consist mostly of interest during the initial years.