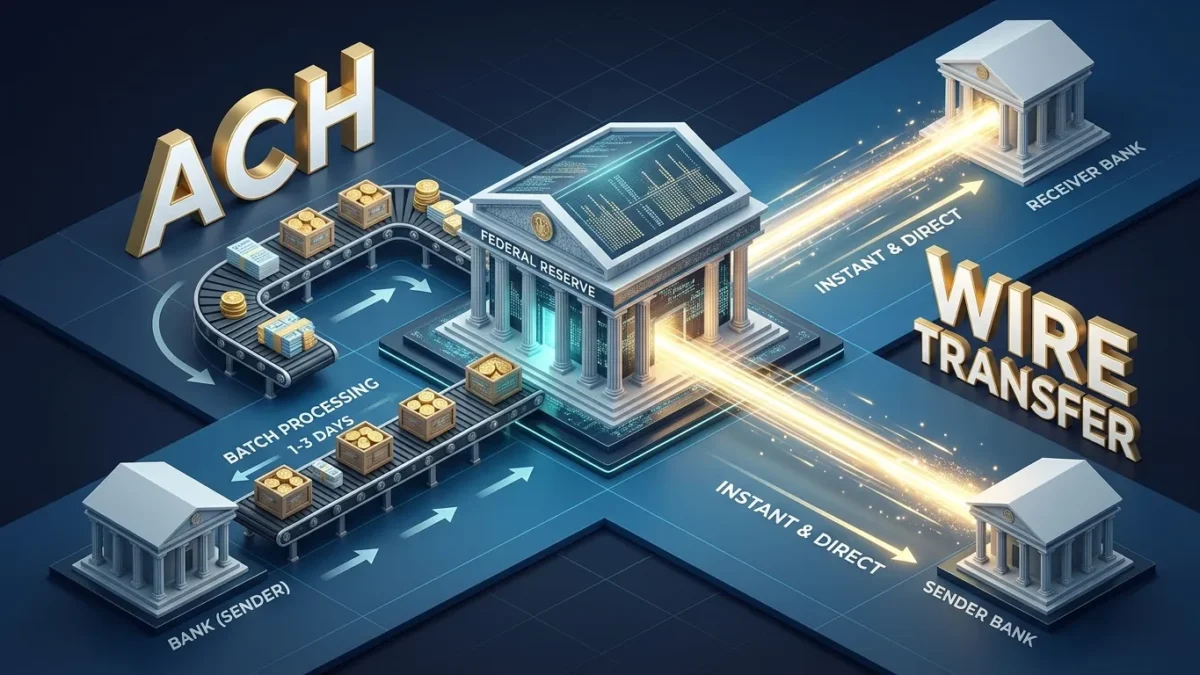
ACH payments clear through batch processing windows managed by an automated clearing house operator, such as the Federal Reserve, which tallies and settles net balances between financial institutions at set times each business day. Instead of sending each transaction immediately, commercial banks group payment instructions into digital files and transmit them in scheduled batches. At BoringMagazine.Co, we explain core banking mechanisms so you know where your money travels during standard settlement windows.
The Mechanics of ACH Batch Processing
When you schedule an Automated Clearing House payment, your bank does not instantly transfer money to the receiving institution. The sender is the originator, and their bank acts as the Originating Depository Financial Institution (ODFI). The ODFI collects outgoing debit and credit requests from customers across several hours.
These transactions include direct deposits, where money moves outward, and automated bill collections, where a company pulls funds from an account. The ODFI groups these entries into electronic batches following rules established by the National Automated Clearing House Association (NACHA).
After assembling the batches, the ODFI transmits the files to an authorized clearing operator. In the United States, transactions run through the Federal Reserve Banks (via FedACH) or The Clearing House (via the Electronic Payments Network). These operators act as central hubs that validate and sort payment instructions across thousands of participating institutions.
How the Federal Reserve Settles Net Balances
Once an operator receives batch files, it sorts each transaction by the destination bank, known as the Receiving Depository Financial Institution (RDFI). The clearing operator then calculates how much money institutions owe one another using multilateral net settlement.
Net settlement differs from moving money for each transfer individually. Instead of exchanging funds for every separate transaction, the clearing house calculates the net difference across all debits and credits among participating banks. The Federal Reserve finalizes these obligations through central reserve accounts that commercial banks maintain at their regional Fed branches.
At designated settlement cutoff times, the Fed adjusts these reserve balances. If a bank owes more than it receives across all morning batches, the Fed debits its reserve account and credits net creditor banks. For a look at how settlement structures differ in financial accounting, review how gross settlement differs from net income.
Key Differences Between ACH and Wire Transfers
While ACH payments rely on batch settlement, wire transfers use Real-Time Gross Settlement (RTGS). In the United States, primary wire systems include the Federal Reserve Fedwire Funds Service and the Clearing House Interbank Payments System.
Under real-time gross settlement, there is no batching or offsetting of balances. When a customer sends a wire transfer, their bank sends the instruction directly to the Federal Reserve. The central bank checks the institution’s reserve balance, deducts the full amount, and credits the receiving bank immediately. Once completed, a wire payment is final and irrevocable.
Because wires require continuous individual processing, banks charge twenty to thirty dollars or more per transfer. Standard ACH payments are usually free for retail consumers and cost pennies for commercial originators. Wires serve urgent, high-value needs like real estate purchases, while ACH handles routine recurring payments.
Real-World Examples: Payroll, Bill Pay, and Mortgage Debits
Consider how direct deposit payroll operates. If workers receive pay on Friday morning, employers transmit payment files to their bank by Wednesday. The bank bundles these instructions and delivers them to FedACH. On Thursday, FedACH routes the records to each employee’s bank, and settlement finishes early Friday morning before the business day starts.
Recurring payments work in reverse through ACH debits. When a mortgage company collects monthly payments, it submits a debit file to pull funds from borrower accounts. In our guide on annual mortgage escrow analysis, we explain how payment changes interact with scheduled withdrawals.
Same Day ACH provides an alternative for faster processing. NACHA allows multiple windows each business day for same-day settlement. However, Same Day ACH includes transaction dollar caps and requires submission before strict morning or midday cutoffs.
Common Misconceptions About ACH Transfer Speeds
Many people assume an ACH transfer takes multiple days because banking technology is outdated. In reality, the clearing house operator finishes batch settlement within twenty-four hours. Much of the remaining delay comes from commercial bank risk policies.
Federal regulations allow consumers up to sixty days to dispute unauthorized ACH debits. Because of this return risk, receiving banks often place temporary holds on inbound transfers before releasing cash for withdrawal. The bank waits to ensure the transaction will not be recalled before making funds available.
Another common mistake is expecting transfers to clear on weekends. Even though online banking tools function twenty-four hours a day, Federal Reserve settlement systems close on Saturdays, Sundays, and federal holidays. Weekend transfer requests remain queued until Monday morning. To learn more about standard banking rules, explore our Finance guides.
When to Consult a Financial Professional
This article provides general financial information for educational purposes and does not constitute formal banking, legal, or tax advice. Financial institutions maintain different cutoffs, processing schedules, and funds availability rules. If you manage corporate treasury functions, handle high-volume payroll, or need help with a disputed transaction, speak with a qualified commercial banker or financial professional about your situation.
FAQ
Why does an ACH transfer take longer than a wire transfer?
An ACH transfer takes longer than a wire transfer because ACH payments are grouped into batches and settled at scheduled intervals rather than processed individually in real time. Banks wait for daily submission cutoffs before sending files to FedACH or the Electronic Payments Network. Wire transfers, by contrast, process individually through Fedwire with immediate settlement and finality.
Can an ACH payment be canceled after it is submitted?
An ACH payment can only be canceled if the bank has not yet processed the batch or if the entry meets strict NACHA reversal rules. Permitted reasons include duplicate transfers, wrong account numbers, or incorrect dollar amounts. Once a valid transfer settles, the sender cannot unilaterally recall the funds and must request a direct refund from the recipient.
What is the difference between FedACH and Fedwire?
The primary difference is that FedACH provides batched net settlement for routine high-volume transfers, while Fedwire delivers real-time gross settlement for individual high-value transfers. FedACH handles payroll and bill payments at low cost with delayed settlement. Fedwire executes immediate, irrevocable transfers directly between bank reserve accounts at higher service fees.